

Elektra Go: Money Transfer
Elektra USA
- 4.5
- 139.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
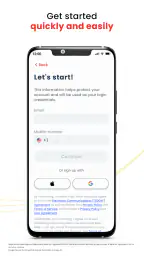
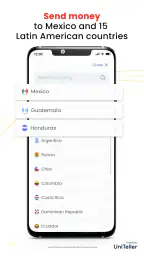
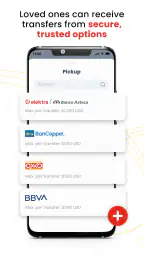
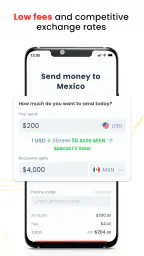
Elektra Go: Money Transfer Pros and Cons
Pros
- Fast transfers between participating Elektra and Banco Azteca services.
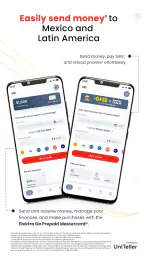
- Convenient option for sending money to Mexico from supported locations.
- Recipients may collect funds at nearby Banco Azteca branches.
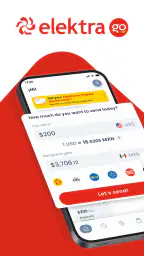
- Simple interface designed for quick money-transfer transactions.
- Transfer status updates help you follow the delivery process.
Cons
- Availability and features vary by country and service region.
- Transfer fees and exchange rates can reduce the amount received.
- Recipients may need valid identification for cash collection.
- Some transfers depend on branch hours and local availability.
- Identity verification may require submitting sensitive personal information.
 Analysis by All-app
Sending money can be one of those tasks I want to finish quickly and forget about. That is the space Elektra Go: Money Transfer is trying to occupy: a finance app from Elektra USA focused on making transfers feel more manageable on a phone. I tested it with a practical mindset rather than treating it as something I would open for entertainment, and my first impression was clear: its value depends less on novelty than on whether it becomes a dependable part of a recurring money routine.
The app is free, aimed at Everyone, and runs on Android devices using version 8.0 or later. It was released on August 29, 2023, and the current version is 9.8.1. Elektra Go has passed the early-adopter stage, with more than 100,000 installs and an average rating of 4.5 from roughly 500 ratings. Those figures suggest that the basic idea is working for a meaningful group of users, although a finance app deserves a more careful look than a casual download.
What Elektra Go feels like after the first week
The first-week appeal comes from having a dedicated place for money transfers instead of relying on a general-purpose banking app or switching between websites and messages. I found that focus useful. When the only job I have in mind is sending money, a specialized app can feel less distracting than a larger financial platform filled with account tools I may not need.
The store summary describes it as fast and secure money transfers, but I would treat those words as a goal rather than a reason to skip basic checking. With any financial app, I look at the recipient details, the amount, and the final review screen before confirming. Speed is helpful only when it does not encourage careless taps. My best early habit was to slow down at the last step and verify every visible detail.
The short description identifies the product simply as Elektra Go, while its fuller name makes the purpose clearer. That distinction matters when searching for it or explaining it to a family member: this is not a budgeting tool, an investment dashboard, or a replacement for a complete bank account. It is a transfer-focused finance app, and that narrow purpose is both its main strength and its main boundary.
During the first week, I would use it for a planned transfer rather than an urgent experiment. Install it before the moment you need it, sign in calmly, and become familiar with the sequence while there is no pressure. That approach also gives you time to notice whether the app fits your phone, your preferred payment routine, and the people you regularly send money to.
One practical scenario shows where it can earn attention quickly. Imagine that I regularly send money to a relative and normally reconstruct the process from old messages, saved browser pages, or memory. A dedicated transfer app can turn that repeated task into a more consistent routine. I still need to check the recipient and amount each time, but I am no longer starting from a blank page or searching through unrelated financial menus.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
That convenience is more meaningful for repeat transfers than for a single occasional payment. If I only send money once every few months, the benefit may be modest. If transfers are part of my normal household rhythm, the app has a better chance of becoming useful after the initial curiosity fades.
Where the focused design helps
I like that Elektra Go can be judged on a straightforward question: does it make my transfer routine easier? A narrowly defined app is often easier to understand than a financial super-app, especially for someone who does not want charts, card controls, credit offers, and account summaries competing for attention.
That focus may also help when assisting a less technical family member. Rather than explaining an entire banking platform, I can describe the app in terms of its central task. The explanation should still include safe habits—use the correct recipient, review the amount, and protect access to the phone—but the mental model is simpler.
Another useful insight is that convenience should be measured over several repetitions, not during the first launch. The first session can feel impressive simply because everything is new. I would judge Elektra Go after using it for transfers in different circumstances: when I have plenty of time, when I am checking details carefully, and when I need to repeat a familiar action without becoming careless.
Where the usual alternatives may be better
A traditional bank app may be the better choice if I want transfers alongside balances, statements, bill payments, card management, and other account services. Keeping everything in one established financial home can reduce the number of apps I maintain. A general payment service may also suit someone whose recipients already use that service and expect its particular workflow.
Elektra Go makes more sense when its transfer purpose matches my needs and when I value a dedicated experience over an all-in-one dashboard. It is not automatically the best answer just because it is free. Free removes a purchase barrier, but it does not remove the need to compare convenience, trust, recipient compatibility, and the effort of maintaining another finance app.
Does it keep earning space month after month?
The long-term question is not whether I can complete a transfer once. It is whether the app remains useful when the novelty has disappeared. For me, recurring value comes from reducing repeated friction: remembering where to start, keeping the process familiar, and avoiding unnecessary detours. If Elektra Go consistently helps with those points, it has a reason to stay installed.
My recommended monthly routine would be simple. Before sending money, I would confirm that I am using the current version, open the app directly rather than following an unfamiliar message, review the recipient information, and check the total before approval. Afterward, I would keep whatever confirmation or record the app presents in a place I can find later. This is not glamorous, but reliable finance tools earn trust through repeatable habits.
The app’s current version is 9.8.1, so keeping it updated is part of responsible use. Updates can change the interface or fix problems, which means I should not assume that a button will always be in exactly the same place. I would avoid starting a transfer for the first time immediately before a deadline after an update; learning the changed flow first is a small trade-off that can prevent avoidable mistakes.
Maintenance is otherwise mostly behavioral. I need to keep my sign-in information protected, avoid sharing access with casual users of my phone, and remove old recipient assumptions from my mental checklist. A familiar name is not proof that the details are still correct. One of the less obvious risks of a convenient transfer routine is autopilot, so I would deliberately pause at the review stage even when the transfer looks identical to earlier ones.
That pause is especially important when a relative asks for money through a new message or under pressure. I would verify the request through a separate channel before using any transfer app. Elektra Go can organize the transaction, but it cannot decide whether a message is genuine or whether the recipient is trustworthy. That distinction is easy to forget when an app promises speed.
The maintenance burden I would expect
For an occasional user, the main burden is remembering how the process works after time away. I would open the app before an urgent need, check that I can access it, and make sure I understand the confirmation steps. This is a better strategy than discovering a sign-in issue while someone is waiting for money.
For a frequent user, the burden shifts from learning to discipline. Repeated actions become faster, but speed can make errors harder to notice. I would create a personal rule that no transfer is confirmed without reading the recipient and amount, even if the transaction is familiar. That rule is more valuable than trying to make every action instantaneous.
Another maintenance question is whether a separate transfer app deserves room beside an existing bank or payment app. I would compare the actual number of money tasks I perform, not the number I imagine performing. If Elektra Go handles a recurring need and saves me repeated searching, keeping it installed is reasonable. If I still open my bank app for every transfer, the extra app may become clutter rather than help.
Because the app is rated for Everyone, it may appear suitable for a broad audience, but that does not mean every user should manage transfers alone. Younger or inexperienced users may need a trusted adult to explain safe account practices and recipient verification. The age label describes general content suitability; it should not replace financial judgment or supervision where appropriate.
What may cause fatigue over time
The first source of fatigue is duplication. If I have to maintain Elektra Go while also using another app for the same transfers, the extra step can outweigh the focused design. This is the clearest situation in which I would choose a different option: when my existing financial service already provides a smooth, familiar transfer workflow and I do not gain a meaningful improvement by switching.
The second is uncertainty at the moment of sending. A transfer app needs to make me feel oriented before confirmation. If I find myself repeatedly wondering whether I selected the right recipient, whether the amount is displayed as expected, or where to find the record afterward, the app becomes mentally expensive even if each individual action is short. I would not ignore that discomfort simply because the app is free.
The third is urgency. Fast transfers sound attractive when I am in a hurry, but urgency is when mistakes are most likely. I would not use the promise of speed as a reason to skip verification, and I would avoid treating the app as an emergency solution until I had already used it successfully in ordinary circumstances. A tool that works well in a calm routine may feel very different under pressure.
There is also the fatigue of changing interfaces. The current version may improve the experience, but updates can require a moment of readjustment. I consider that a normal cost of using a maintained finance app, not an automatic flaw. Still, users who dislike any change may prefer a service they already know, especially if their transfers are infrequent.
Privacy and security habits can create another kind of friction. I would use a trusted network, protect the device, and avoid entering financial information while someone is watching. These precautions apply to any transfer service, but a dedicated app can make the process feel routine enough that I stop thinking about them. The safest workflow is the one that stays careful without becoming so complicated that I abandon it.
Who will get the most from it?
I see the strongest fit for people who send money repeatedly and want a focused mobile route. It may also suit users who find full banking apps overwhelming and prefer a narrower purpose. Families can benefit when several people understand the same basic process, provided each person treats recipient verification and account protection seriously.
I would be more cautious about recommending it to someone who rarely transfers money, already has an excellent workflow through a bank, or needs a broad set of financial tools in one place. It is also not the right choice for anyone expecting a budgeting system, investment management, or a complete replacement for their primary financial institution. The category matters: Elektra Go is a transfer app, not an entire personal-finance ecosystem.
The developer, Elektra USA, gives the product a clear identity, but I would still make my decision based on the actual routine rather than the name alone. A recognizable developer can make an app easier to consider, yet my lasting trust would come from consistent use, understandable confirmations, and a workflow that helps me avoid mistakes.
My long-term verdict after the novelty fades
I think Elektra Go: Money Transfer earns lasting space when transfers are a regular part of my life and its focused approach genuinely reduces repeated effort. Its strongest quality is not that it makes money management exciting; it is that it can give one recurring task a predictable home. That is a modest benefit, but modest benefits are often the ones that survive after the first week.
Its free price makes trying it easy, and the 4.5 average rating from about 500 ratings shows that many users have responded positively. I would read that as encouragement, not as a substitute for my own checks. Finance apps deserve a higher standard than games or social tools because a confusing step can have real consequences.
My practical recommendation is to test it during a normal, non-urgent transfer and decide afterward whether it is clearly easier than the alternative I already use. Keep the app if it shortens the path without making verification harder. Remove it or stay with another service if it creates duplicate work, uncertainty, or a second maintenance routine with no clear payoff.
The best reason to keep Elektra Go installed is a repeatable habit: open it intentionally, confirm the recipient and amount, complete the transfer, and retain the transaction record in a way that works for you. The worst reason is simply assuming that a fast process is automatically a safe one. For me, its lasting value depends on focused convenience paired with deliberate checking.
Overall, I would recommend giving it a fair trial to people who make recurring transfers and want a dedicated finance app on an Android device running version 8.0 or newer. I would not recommend switching blindly from a bank or payment service that already works well. Elektra Go is most convincing when it solves a specific repeated problem; outside that use case, its narrow focus may be less useful than the broader alternative already in your pocket.
Frequently Asked Questions
What is Elektra Go: Money Transfer used for?
Elektra Go: Money Transfer is designed to help users send money, manage transfers, and access related financial services through a mobile device. Depending on your location and account eligibility, the app may support domestic or international remittances, transfer tracking, recipient management, and notifications. Available features can vary by country, so check the service details shown in the app before starting a transaction.
Do I need to create an account and verify my identity?
Yes, users generally need to register an account before using Elektra Go’s money-transfer services. The app may request personal information, a valid phone number, identification documents, or additional details required by financial regulations. Verification can take time, and access to certain transfer limits or services may depend on completing the identity-check process successfully.
How much does Elektra Go charge for sending money?
Transfer fees are not necessarily the same for every transaction. The final cost can depend on the amount sent, destination country, payment method, delivery option, exchange rate, and any promotional offer available at the time. Review the confirmation screen carefully before approving a transfer, because it should display applicable fees, the exchange rate, and the expected amount received.
How long do transfers take, and can I track them?
Delivery times depend on the destination, selected payout method, operating hours, verification requirements, and possible banking or compliance checks. Some transfers may arrive quickly, while others can take longer than expected. Elektra Go typically provides transaction details or status updates inside the app, allowing you to monitor whether a transfer is pending, completed, delayed, or requires further action.
Is Elektra Go safe to use, and what should I do if there is a problem?
Elektra Go may use account authentication, transaction confirmation, and security controls to help protect financial activity, but users should still take precautions. Download the app only from an official store, avoid sharing passwords or verification codes, and check recipient details before sending money. If a transfer is incorrect, delayed, or unauthorized, contact official support promptly using the in-app or verified support channels.


